The taxable brokerage account
What it is: an ordinary investment account. No contribution limits, no age rules, no restrictions on what you buy or when you sell.
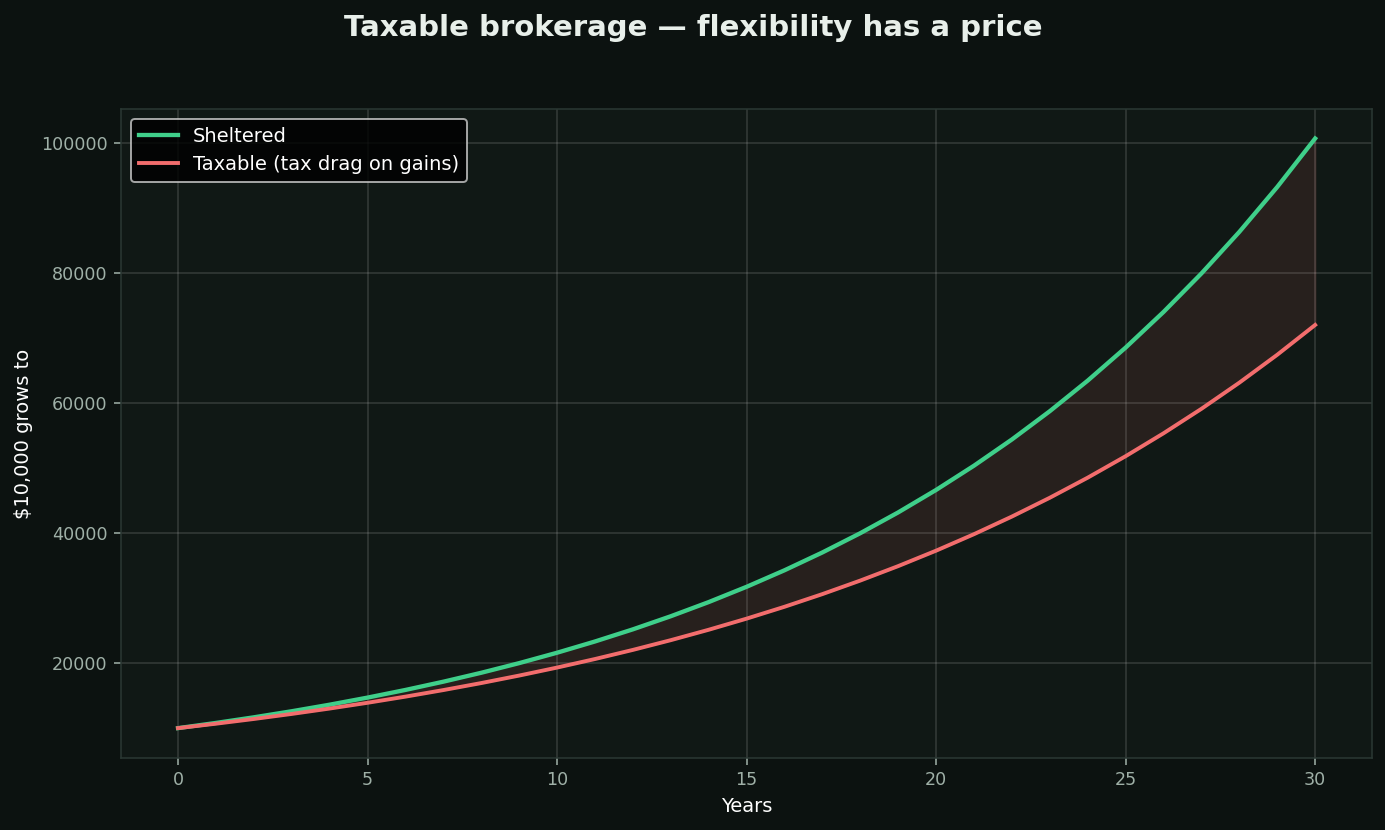
What it costs: tax as you go. Dividends are taxed the year you receive them, and gains are taxed when you sell. That yearly drag compounds against you.
Where it genuinely wins:
• Money you might need before retirement age
• After you have maxed the sheltered accounts
• Tax-loss harvesting — only possible here
• Long-term gains are taxed at lower rates than income
• Heirs may receive a stepped-up basis
The practical rule: it is the account you use *after* the others, not instead of them — unless you need the liquidity.
Chart: the same 8% return with and without annual tax drag.